Transaction Center
Time to bring it home. Find zipForm®, transaction tools, and all the closing resources you'll need. Except for the champagne — that's on you.
Get a roundup of weekly economic and market news that matters to real estate and your business.
View the latest sales and price numbers. Find out where sales will be in upcoming months.
Housing Market ForecastGain insights through interactive dashboards and downloadable infographic reports.
Catch up with the latest outreaches and webinars by the Research and Economics team.
C.A.R. conducts research with members and consumers on a regular basis to get a better understanding of the housing market and the real estate industry.
California Model MLS Rules, Issues Briefing Papers, and other articles and materials related to MLS policy.
Looking for information on how to file an interboard arbitration complaint? You've come to the right place! Find the rules, timeline and filing documents here.
Information for members who serve as volunteers in C.A.R.'s Professional Standards programs
Missed a training? Check here for previous Professional Standards webinars.
Summaries and photos of California REALTORS® who violated the Code of Ethics and were disciplined with a fine, letter of reprimand, suspension, or expulsion.
The most recent edition of the Code of Ethics and Standards of Practice of the National Association of REALTORS® along with other important links to NAR information.
Find the tools and information needed as a Professional Standards Administrator
Professional Standards Film FestivalUpdates on C.A.R.'s legislative advocacy efforts in Sacramento.
Ballot MeasuresIssues briefing papers, handbooks and other background materials on local policy issues that affect real estate.
CREPAC, LCRC, IMPAC, ALF and the RAF comprise C.A.R.'s political fundraising arm.
The RAA: Protecting REALTORS® and Homeownership REALTOR® Action FundLearn how you can make a difference, by getting involved yourself or by passing along valuable information to your clients.


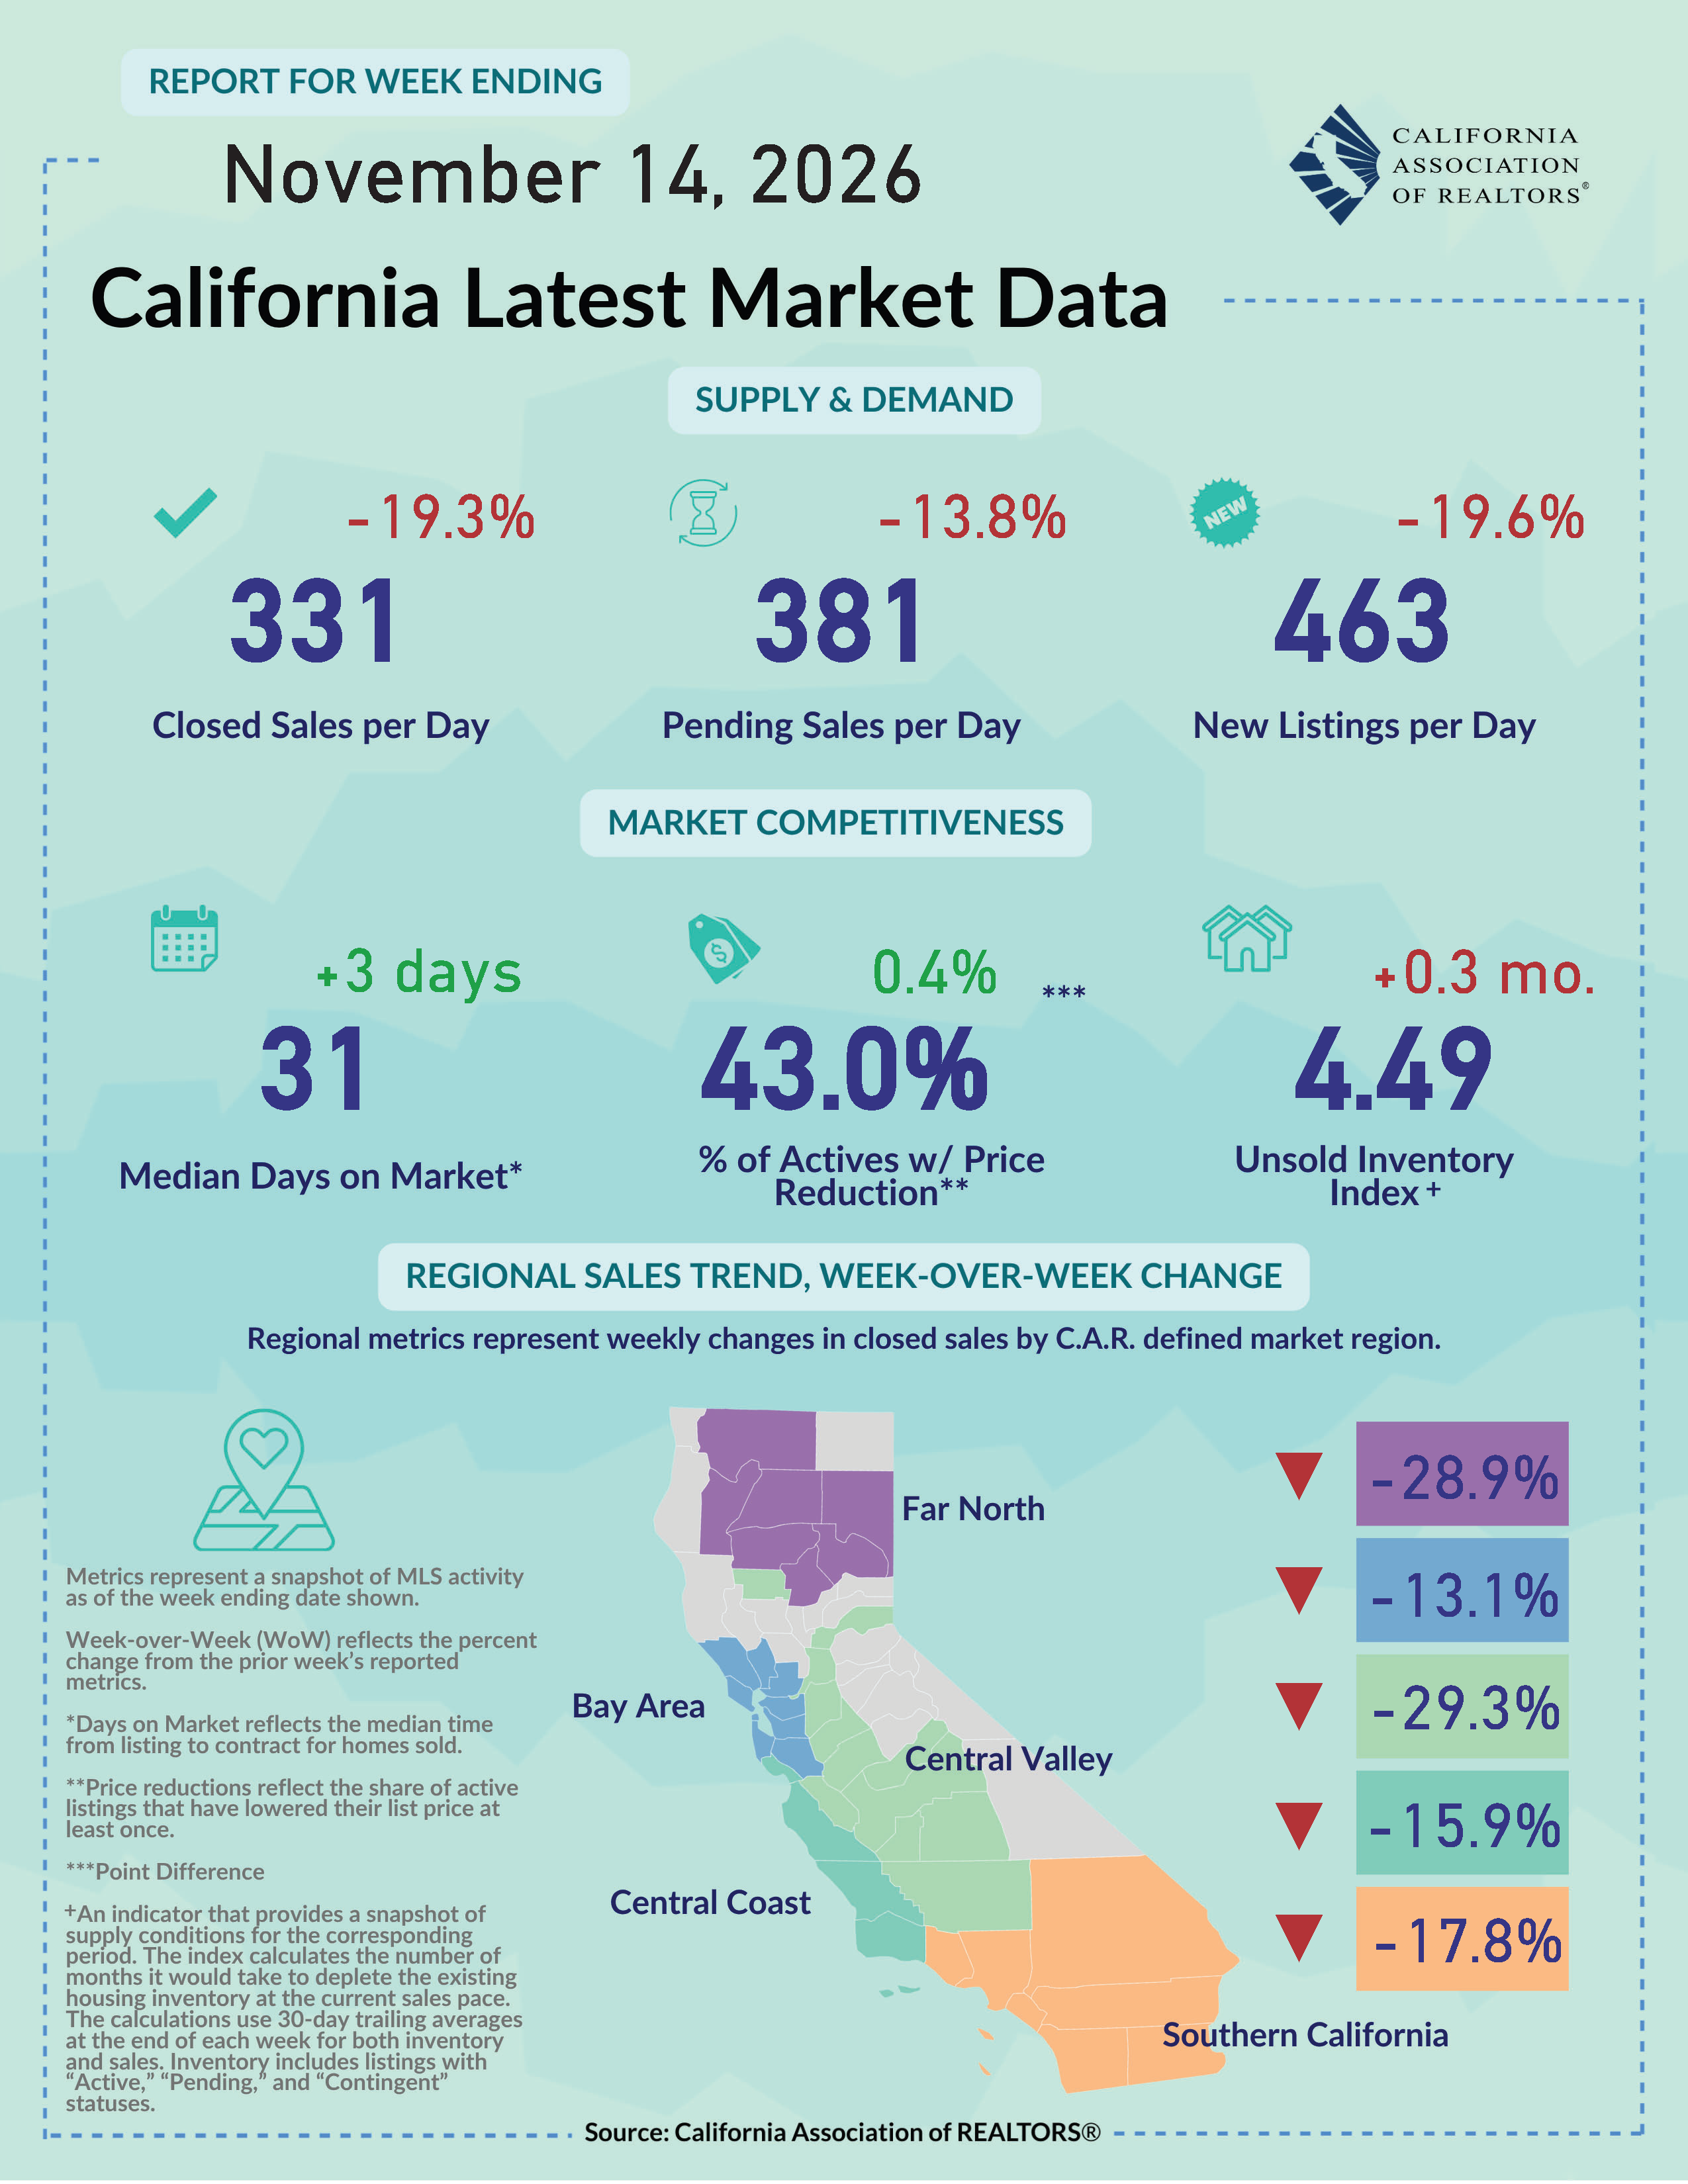
CALIFORNIA HOUSING MARKET MINUTE
Get the latest insights on California’s housing market with C.A.R.’s Market Minute. Follow key real estate trends, including home sales, prices, inventory, mortgage rates, and economic conditions affecting buyers, sellers, and REALTORS®.
November 16, 2026
Prices rose more than expected in October, and higher interest rates will keep housing activity soft through year-end. While inflation and financial market volatility are unlikely to settle in the near term, encouraging signs point to gradual improvement in both the economy and the housing market: small business uncertainty has eased, inflation expectations have stabilized, and holiday spending remains resilient. With price growth expected to remain mild and rates projected to ease, affordability challenges should lessen and demand could pick up in early 2027.
|
October inflation comes in hotter than expected. Inflation remained elevated as costs for goods and services rose more than expected in October, with the headline Consumer Price Index (CPI) up 0.4% for the month after an increase of 0.6% in September. Before the release of the latest consumer price report, economists surveyed projected a 0.3% increase. Core CPI – the measure of change in prices excluding volatile food and energy components - increased 0.3% month-over-month and was also higher than the consensus expectations of a 0.2% gain. Despite gas prices falling in recent weeks, the corresponding index was still up 1% from September. Food costs also surged 0.5%, while shelter costs went up by 0.3%. Annual inflation figures are not available due to lack of data from last October as a result of the government shutdown that prevented sufficient data to be collected. The hotter than expected inflation report raised the question of whether the Fed has done enough to contain price pressures. Before the release, Fed Governor Waller said that a hot inflation report could push him toward advocating for a half-point increase in December. The US 10-year treasury yield has climbed up by more than 20 basis points since the release and the average 30-year fixed mortgage rate has erased almost all improvement seen over the past five weeks and has gone back up to 7.50% last Friday, according to Mortgage News Daily. Higher interest rates will likely keep housing activity soft for the last few weeks of 2026. Small business optimism steady as uncertainty declines in October. Business optimism hardly changed last month, as the NFIB Small Business Optimism Index for October dipped 0.1 points from September to 97.8, slightly below its 53-year average of 98.0. Inflation and labor shortages remained challenges to business owners, while rising borrowing costs and weaker earnings continued to have an adverse impact on business activity. The short-term business outlook turned slightly more positive though, as a net 8% of owners expected better conditions in the next six months, an increase of 2 points from September. Inflation metrics deteriorated again last month, with the net percent of owners raising average selling prices up 2 points to 33%, and the net percent who planned to increase prices in the next three months jumped 6 points to 37% - the highest level since July 2022. The uncertainty level improved last month though as its index fell 6 points to 84, reaching the lowest reading in 10 months. With the midterm elections now behind us, there should be more clarity on the small business outlook, but inflationary pressure and fluctuating labor market conditions will likely weigh on the overall business economic environment in the near term. Home equity continues to grow as prices rise. With the statewide median price projected to rise for the straight year, home equity gain in California remained near the record high in 2026. Results from C.A.R.’s 2026 Annual Housing Market Survey suggest that home sellers typically pocketed a net cash gain of $350,000 from the sale of their homes in 2026, unchanged from the gain recorded in 2025. In terms of the purchase price, it is a 93% gain. Home sellers who lived in their house for less than five years earned an 8.8% profit from their sale, while those who lived in their house for five or more years earned a 110.2% profit. About one out of twenty (5.2%) sellers had a net loss from their home sale this year, up from last year’s 5.0% but remained below the long-run average of 9.0%. Once again, the study show that homeownership remains a reliable wealth builder. Holiday spending projected to grow moderately mostly due to higher prices. Consumer spending during this holiday season will remain resilient despite elevated inflation and slower job growth, according to Visa Business and Economic Insights’ 2026 U.S. Holiday Spending Outlook. U.S. holiday retail sales are projected to increase 4.5% year over year in November and December - the strongest growth since 2021, as higher travel costs reshape budgets while shoppers prioritize physical gifts over experience. Consumers plan to spend an average of $777 on holiday gifts, an increase of 5.6% from 2025. Much of the increase reflects higher prices though, as prices of holiday related goods are expected to climb 3.4% this year, leaving inflation-adjusted holiday spending with an increase of just 1.1%. With persistent inflationary pressure and lingering economic uncertainty, consumers remain price-conscious, and many of them plan to shift toward cheaper brands or retailers. Overall, the outlook points to a healthy but uneven holiday season, with affluent households in a stronger position to sustain discretionary spending. Labor market outlook remains mixed but inflation expectations stabilized. Perceptions about the labor market outlook were mixed with more believed that the U.S. unemployment rate will be higher a year from now, according to the latest New York Fed’s Survey of Consumer Expectations. The mean probability that the unemployment rate will be higher one year from now increased by 1.4 percentage point (ppt) to 45.3%, the highest reading since April 2020. Meanwhile, respondents were also more positive about job searching as the mean perceived odds of finding a job if one’s current job was lost inched up by 0.4 ppt to 46.5% and reached the highest point since November 2025. Recent encouraging jobless claims numbers, along with solid Q3 GDP numbers, might have provided more optimism for job seekers in October. Inflation expectations also appeared to be stabilizing as households’ prediction on price growth were unchanged at the short-, medium-, and longer-term horizons. The flattening in inflation expectation was due partly to declines in gasoline prices in the past weeks. While the most recent CPI report suggests that inflation could remain elevated in coming months, price growth should begin moderate in early 2027 once the Middle East conflict is resolved. Note: This summary report gets updated every Monday by 6:00 pm PST. Feel free to email us at [email protected] if you have any questions and/or feedback.
|
|